How can a Swiss or European universal bank help transform death from a fragmented administrative burden into a secure transition of responsibility, without claiming authority over inheritance law or a customer’s private life?
A conversation with my friend Ali Soy, who runs digital-age.ch, began with an uncomfortable contradiction.
A customer can open a bank account digitally, sign contracts remotely, manage investments across borders and use e-banking at any hour. Yet when that customer dies, the people left behind enter a world of copied certificates, unclear authority, telephone queues and institutions that each handle only their own small part.
Imagine a daughter living in London whose father dies in Zurich, leaving her mother behind. Before she has processed the news, she may need to establish whether rent is due or whether mortgage interest and scheduled amortisation can continue to be paid. She may need to make sure that heating, electricity and insurance remain active, identify direct debits and understand whether her mother has enough immediate access to money for everyday life. She may also need to learn whether she is entitled to ask the bank for information at all, or whether decisions must be made jointly with her mother and other heirs.
Perhaps there is an apartment in Italy. Perhaps there is a small business in Germany, where payroll cannot wait for probate. Perhaps another heir lives in Singapore. Perhaps the deceased had cloud storage, subscriptions and digital assets that nobody else can identify.
The problem is not that these tasks are impossible. The problem is that every institution solves only its own small part. The heir becomes the manual integration layer between them.
That is an extraordinary failure of the digital economy.
A burden that will grow
This is not a niche problem for estate lawyers. It will become a larger economic and social burden as Western societies age.
In 2024, people aged 65 or over accounted for 21.6 percent of the European Union population. Eurostat expects the share to reach 32.5 percent by 2100. More older people means more estates. It also means more estates involving long lived contractual relationships, complex asset structures, vulnerable surviving spouses and family members living in other jurisdictions.
At precisely the moment when a family needs clarity, institutions provide fragmentation. The bank requests one set of documents. The insurer requests another. The utility provider needs a contract reference. A foreign property authority may require a local notary, an apostille and a certified translation. A social platform may offer memorialisation but not access.
The cost is not limited to administration. Unmanaged obligations can lead to missed payments, interrupted coverage, dormant subscriptions, delayed claims and avoidable fraud exposure. The human cost is more serious: a surviving spouse may have neither the confidence nor the information to navigate the system at the moment of greatest vulnerability.
This is not primarily a technology gap. It is an ownership gap. No institution owns the transition between death and the orderly continuation, transfer or closure of responsibilities.
Authority, not access
The obvious answer is wrong. The solution is not broad access to the deceased person’s data.
A death certificate proves that somebody has died. It does not prove who may act for the estate, whether several heirs must decide jointly, whether a will exists, whether an executor has been appointed or whether a claimant may do more than ask for information.
A properly designed bereavement journey combines four things: verified identity, legally recognised estate authority, informed consent for the specific action and document integrity.
Verified identity answers who is making the request. Estate authority answers what that person may legally do, for whom, for what purpose and for how long. Informed consent answers which action that person has deliberately chosen. Document integrity proves that the instruction, evidence and signature are authentic, unaltered and auditable.
Only when all four conditions are met should an institution disclose sensitive information, transfer a service, cancel a contract or release estate assets.
This is the missing infrastructure of a digital society: not universal access, but Portable Trust. The relevant question is not “Who inherits everything?” It is “Can this identified person perform this defined action, for this purpose, until this authority expires?”
Switzerland’s planned eID and trust infrastructure could support this approach. The Confederation expects the trust infrastructure to become operational in the first half of 2027 and intends it to support electronic credentials issued by public bodies and private entities. A future estate authority credential could prove that a person may request account information, pay estate expenses or jointly transfer a household contract, without exposing the entire estate file.
A cross border continuity layer
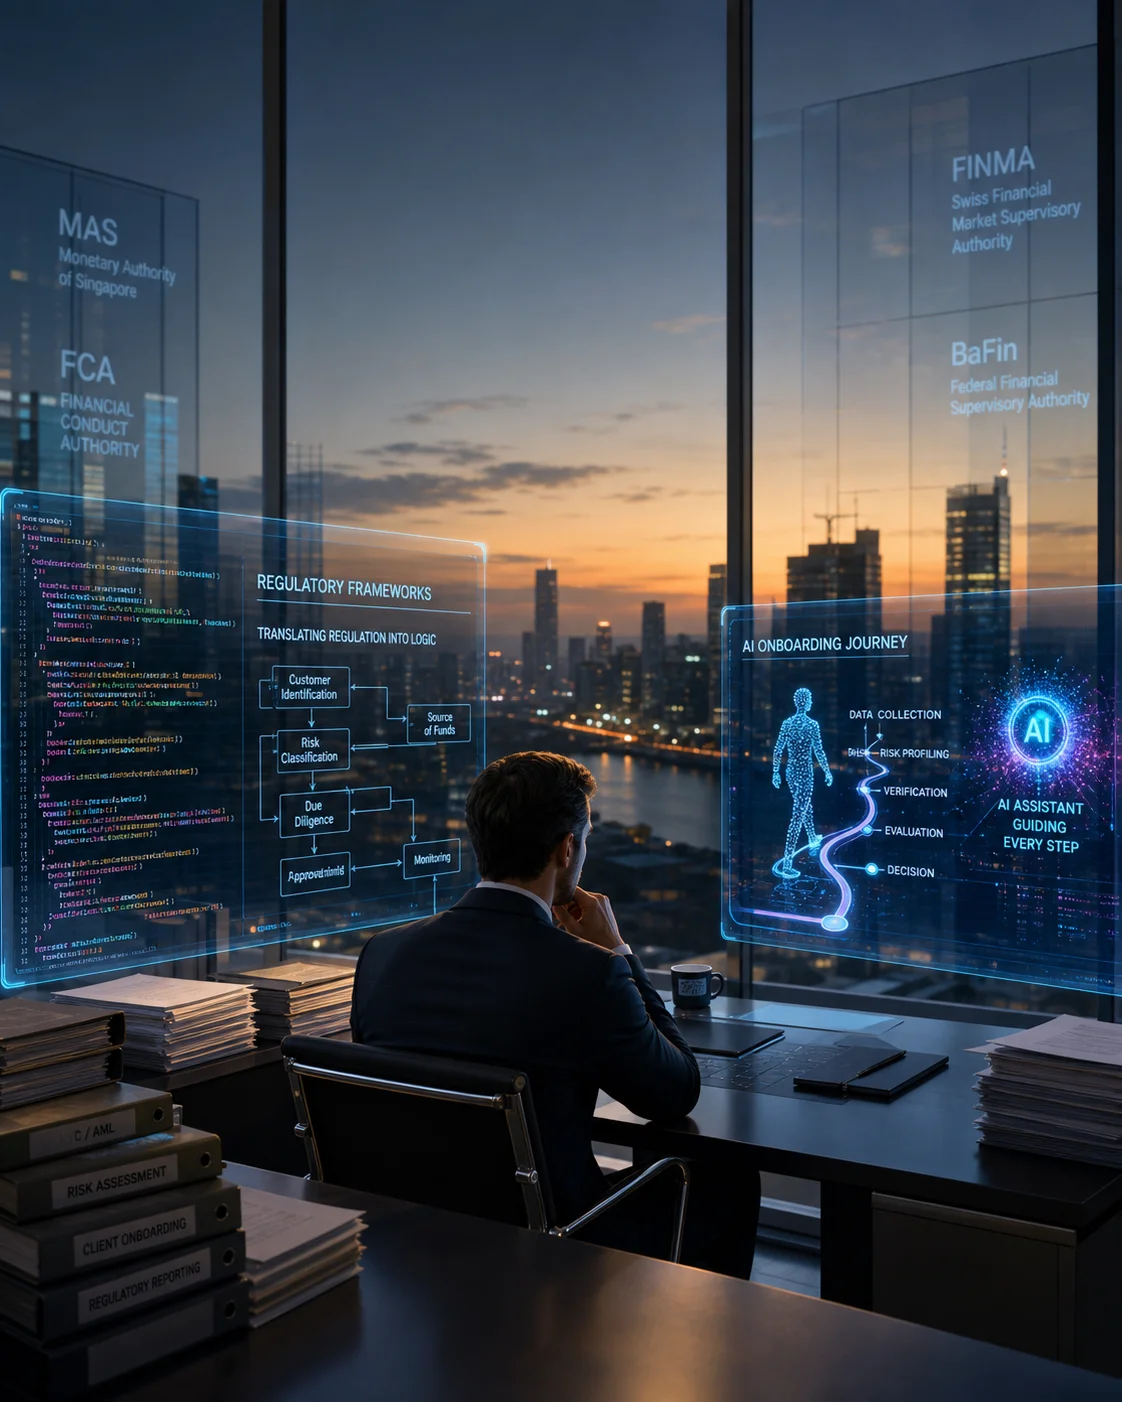
Call the resulting model Continuity. It is not a bank owned super platform, and it does not automate inheritance law. It is a public private trust layer that turns a verified death event into a guided and limited journey for authorised people.
Public authorities would provide the trusted rails: confirmation of death, identity verification and legally recognised authority. Banks, insurers, pension providers, utilities, telecom companies, landlords and digital platforms would retain responsibility for their own decisions.
The heir would encounter one journey, not twenty disconnected procedures. The first question should not be “Which form do you need?” It should be “What needs attention today?”
That journey should distinguish between people, home, money, digital life and legal estate. It should prioritise household stability before administrative completeness. It could show confirmed relationships returned by participating organisations and, with prior customer consent, flag possible relationships such as recurring payments that may indicate an insurance policy or subscription.
The boundary matters. A bank may use data to help a family identify a possible obligation. It must not turn payment history into a hidden map of the deceased person’s private life.
Parts of this model already exist. Norway’s Digital Estate service offers authorised heirs guidance and an overview of registered information about assets and debts. Australia’s Death Notification Service lets users notify multiple organisations through one online notification. New Zealand’s myTrove similarly enables a secure, single notification to participating government agencies, banks, insurers and other providers.
The difficult cases are international. A Swiss resident may leave behind a home in Zurich, property in Italy, a company interest in Germany, pension assets in the United Kingdom and heirs in Singapore. No platform can abolish national succession law, local property rules, tax obligations or notarial requirements.
But it can make borders visible before they become expensive surprises. It can identify relevant jurisdictions, expose joint decision requirements, sequence urgent tasks and route the family to the right notary, lawyer, fiduciary or tax adviser.
The aim is not borderless inheritance. It is an end to invisible borders.
Banks can lead
Banks are in a uniquely strong position to lead this transition. They already manage high consequence decisions, identity verification, fraud prevention, documentation and risk. They understand mortgages, household liquidity, recurring payments, investments and the financial vulnerability that can follow a death.
For many families, the bank is among the first institutions they contact. That makes it a natural estate navigator.
A bank can protect assets, explain immediate options, support legitimate estate payments and identify possible recurring obligations where the customer gave consent. It can provide human guidance when a surviving spouse needs everyday liquidity, when heirs need to act jointly or when a foreign property or business creates complexity.
The bank should not claim to decide inheritance law or hold the full story of a customer’s private life. Its role is to connect, not capture. It can convene an ecosystem of insurers, pension funds, public authorities, utilities, telecom providers, landlords, notaries and cross border advisers.
This changes the bank’s role from product provider to trusted life transition partner. The measure of success is not retained balances or sales to a surviving spouse. It is fewer repeated document requests, fewer missed obligations, fewer avoidable losses and more clarity for families.
AI should clarify, not decide
An AI companion could make Continuity materially easier for heirs. It could translate legal or provider language into plain English, German, French or Italian, or other. It could explain why a document is required, identify missing information, prepare provider specific requests, surface potential cross border issues and coordinate tasks between heirs.
Its role must remain deliberately limited. It should not determine who inherits, interpret a contested will, release assets or cancel high consequence contracts. The AI companion for the heirs should prepare, explain, prioritise and protect. Verified heirs, authorised institutions and qualified professionals must decide and execute.
That is not merely a design preference. Human oversight is a core EU requirement for high risk systems, intended to ensure that people can understand, challenge and override consequential automated outputs.
The strongest objection
Inheritance is too sensitive, too country specific and too legally complex for standardisation. A shared journey could create false confidence, facilitate fraud or reduce complex family circumstances to a simplistic checklist.
That objection is valid if the ambition is to automate inheritance law. It is not valid if the ambition is to standardise the trust components beneath it:
- Verified death,
- verified identity,
- limited authority,
- secure document exchange and
- transparent status.
The system would not decide who inherits. It would help each institution apply its own rules without forcing bereaved families to integrate the economy manually.
Consequences
The call to action is not for one bank, insurer or technology company to build another closed platform. It is for banks, insurers, pension funds, public authorities, utilities, telecom providers and digital platforms to agree on common trust standards: how death is verified, how estate authority is proven, how limited permissions are expressed and how institutions exchange only the data they genuinely need.
- Governance. A bank should support common standards for verified death, limited estate authority, revocation, auditability and joint decision making. No sensitive action should occur without verified identity, valid authority, explicit consent and evidence integrity.
- Customer experience. Bereavement should be designed as a distinct customer journey. The first days should focus on household stability, immediate liquidity and vulnerable dependants before estate distribution or account closure.
- Data. Recurring payment data should be treated as a consent based clue, not as permission to profile the deceased. Banks should guide and connect, while every institution remains responsible for its own legal and risk decision.
Switzerland has a strong financial centre, high institutional trust, established compliance capabilities and an emerging eID trust infrastructure. The question is whether these strengths will remain isolated assets within individual organisations or become the foundation of a better societal service.
In a society that has digitised almost every part of life, can we continue to accept that grieving families must still connect the economy by hand when a life ends?
Quellen
- Eurostat: Population structure and ageing (2025)
- Swiss Confederation: New timeline for the introduction of the eID and trust infrastructure (2026)
- Altinn: Digital Estate (2026)
- Service NSW: Australian Death Notification Service (2024)
- myTrove: Notify Organisations After a Death (2026)
- European Commission: AI Act Service Desk, Article 14, Human Oversight (2026)