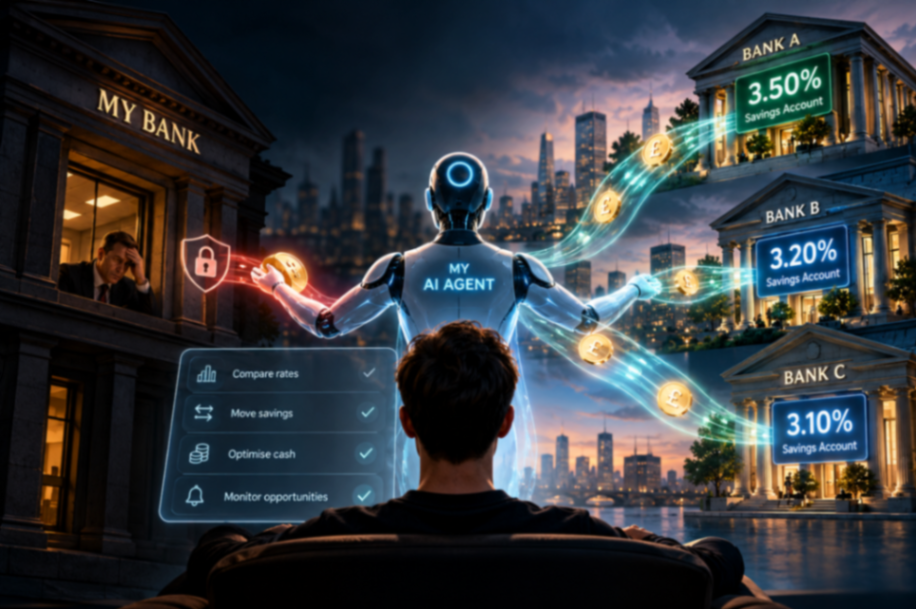
Revolut wants to turn millions of transactions into financial intelligence. US banks are blocking external AI agents from accessing customer accounts. Behind these developments lies a bigger threat to traditional banking: customers may soon have software that finds better financial deals and acts on them.
Banks have always benefited from customers who leave their money where it is. Switching accounts takes effort, comparing interest rates is tedious, and most people have better things to do. That inertia helps banks retain deposits, including those paying relatively little interest.
Now imagine a personal AI assistant that checks interest rates across banks, calculates the benefit of switching and offers to move your savings. No paperwork, no searching, no forgotten intentions. A customer who never bothered to switch banks could suddenly become the most demanding customer in the market.
This is no longer just a theoretical threat. Banks are already confronting agents attempting to access accounts and conduct transactions. And they are pushing back.
Banks Are Blocking Open Banking Access for AI Agents
On 16 October 2026, Charles Schwab CEO Rick Wurster confirmed, that his company was blocking unauthorised AI agents attempting to move customer money, including Meta’s Muse.1 Other major US institutions, including JPMorgan Chase, Citi and Bank of America, have also restricted external agents. Reuters reported further concerns on 22 October about agents accessing accounts with customer credentials and apparently taking actions beyond user instructions.2
Banks have legitimate reasons to intervene. Password sharing, unclear authorisation and unpredictable transactions create serious security and liability risks. A customer’s permission to use an assistant does not automatically make that assistant a securely authenticated or authorised banking participant.
But there is a second concern. Agents that continuously compare interest rates could undermine one of banking’s quiet advantages: customer inertia. In September, The Wall Street Journal highlighted how automated switching could threaten banks’ low cost deposits.3
The distinction matters. Reports establish that banks are blocking unauthorised agents. They do not establish that banks are blocking them primarily to preserve deposit margins, or that autonomous deposit switching is already widespread. Nevertheless, the commercial threat is obvious. If customers stop being passive, banks may have to compete for their money every day.
Revolut wants to know what happens next
While established US banks are restricting external access, Revolut is pursuing another route. On 9 October, 2026 CEO Nik Storonsky revealed, that Revolut had developed proprietary AI models trained on customer transaction data. With 30 to 40 million transactions processed daily, the company sees an opportunity to build technology businesses beyond traditional banking.4
Revolut has not demonstrated that these models can reliably predict individual financial futures. But transaction data can potentially reveal changes in income, spending, debt and savings. Combined with information from other sources, it could support earlier warnings about financial stress or more personalised financial guidance.
This creates two competing models of future banking:
- Banks can use their data to anticipate what customers might need.
- Independent assistants can use customer-authorised information to compare institutions and recommend where money should go.
One model strengthens the bank’s relationship with the customer. The other could weaken it. And the second model may prove more disruptive. The bank that holds your money may no longer control the decision about where it belongs.
The Regulator sees the bigger Shift
Britain’s Financial Conduct Authority is already examining this change. Its July 2026 Mills Review found that around 11 million UK adults would be likely to use AI capable of acting autonomously within predefined goals. The review explicitly considers how such systems could reshape customer journeys, competition and market power.5
The FCA is not demanding that banks allow unrestricted access to autonomous agents. Nor has it introduced a general obligation to warn customers about predicted financial difficulties. Its existing Consumer Duty nevertheless places customer outcomes and foreseeable harm at the centre of relevant regulatory expectations.
The regulatory challenge is becoming concrete: How can a bank verify that an agent genuinely represents a customer, understand what it is authorised to do and determine who is responsible when something goes wrong? Simply blocking every external agent cannot be a permanent answer if customers increasingly expect to delegate financial tasks. But allowing unrestricted access through shared passwords is equally indefensible. The next challenge is trusted, limited and revocable authorisation.
AI Agents in Banking: Put the Customer Relationship up for Grabs
Governance. Banks will need to distinguish between an agent that can read account information, one that can recommend a transaction and one authorised to execute it. These permissions require different controls, transaction limits and accountability.
Customer trust. The winning proposition may be an assistant that warns customers about financial risks, identifies better offers and acts only within agreed boundaries. Banks must decide whether to provide that service themselves or allow independent providers to compete for the role.
Business model. If switching becomes effortless, deposits could become more sensitive to interest rate differences. Banks that rely on customers not comparing alternatives may face pressure on margins. That remains a scenario, but the underlying economic logic is straightforward.
The developments at Revolut, Schwab and the FCA point to the same shift. Financial intelligence is moving closer to the customer, while the authority to act on that intelligence is becoming contested.
Banks have good reasons to protect their systems. They also have good reasons to fear a customer who can compare every offer and move money without effort. The uncomfortable question is whether banks will build the infrastructure for customers to act freely, even when the best financial decision is to move their money elsewhere.
Sources
- Bloomberg: US Banks Block AI Agents Attempting to Move Money for Customers (2026)
- Reuters: US banks are blocking third-party AI agents access to customer accounts, sources say (2026)
- The Wall Street Journal: Lazy Customers Are Great for Banks. Could AI Change That? (2026)
- Reuters: Revolut aims to become global tech company beyond banking, CEO says (2026)
- Financial Conduct Authority: FCA publishes landmark review into impact of AI on retail financial services (2026)